[17 November 2026]
Having children changes more than your daily routine. It can reshape your career, reduce your income and quietly alter your long-term financial future. It doesn’t have to, explains Stacy Saber of Pinnacle Wealth Management.
Stacy sees many people who have taken a career break to have children but not put the plans in place to keep their finances on track.
For Sam Shand, Pinnacle’s own Operations Director, her first child was part of the plan. The second however was not.
Like many couples, Sam and her partner adapted as family life changed. But time away from her career left a financial gap that did not disappear when she returned to work.
Now, she describes herself as ‘playing catch-up’.
Financial Adviser Stacy however doesn’t believe women should simply have to accept that as the price of having a family.
Too often, the financial impact of a career break is only confronted years later, when valuable time has already been lost. The right expertise, introduced earlier, can make those consequences visible and give families more choices early on about what to do next.
The conversation needs to start earlier
Financial planning shouldn’t begin only when someone feels wealthy enough, old enough or worried enough. It should start with understanding what you want your money to help you achieve, particularly when major life changes could affect those plans.
A career break should not become a lifelong financial penalty
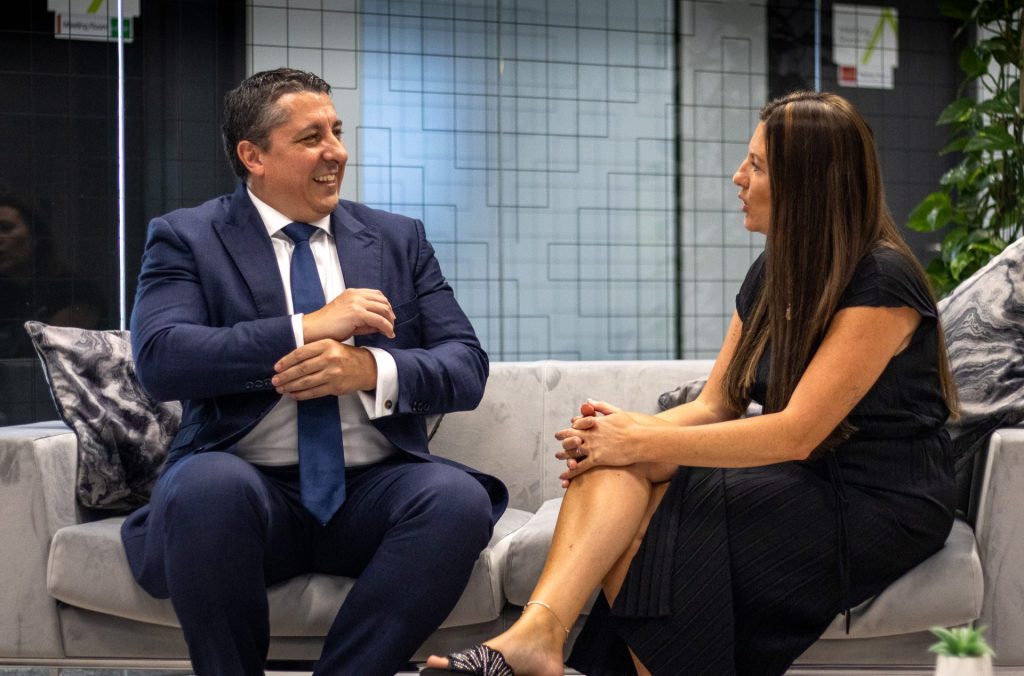
In our short video, you can see Pinnacle Financial Adviser Stacy talk to Sam, referring to the Women and Wealth Report 2026 by St. James’s Place and the long-term impact of taking time away from work to raise a family.
A career break can affect far more than the salary you lose out on at the time. It may also mean:
- Fewer workplace pension contributions
- Lower employer pension contributions
- Less disposable income available to save or invest
- Slower career and salary progression
- Reduced National Insurance contributions
- Less time for investments to grow
Individually, each of these may appear manageable. Over several years, however, their combined effect can create a significant long-term gap.
The St. James’s Place Women and Wealth Report 2026 reflects this reality. Career breaks and caring responsibilities continue to affect how women earn, save, invest and prepare for the future.
The Report explains that Women between the ages of 55 and 59 have, on average, pension savings worth around half those of men of the same age.
The value of an investment with St. James’s Place will be directly linked to the performance of the funds you select and the value can therefore go down as well as up. You may get back less than you invested.
Could you put a future child into a financial plan?
Nobody can predict exactly when or if they will have children, how long they may take away from work or how family life will unfold.
But you can explore what different possibilities might mean financially.
Stacy explains that, had these conversations taken place before Sam and her husband started a family, the potential costs could have been incorporated into a financial plan. This might have included:
- The potential loss of income during maternity leave or a career break
- Childcare and everyday family costs
- School or university fees
- Changes to pension contributions
- The impact of one parent reducing their hours
- The amount the family might need to save or invest beforehand
Planning wouldn’t have removed every uncertainty. It could, however, have made the financial effects more visible, identified ways of building wealth before salaries are reduced and given the family more financial structure.
A Pinnacle LifePlan can model different scenarios, helping people to see how decisions made today can affect their financial position in five, ten or twenty years.
When it comes to investing, time matters
As Stacy explains in the video, one of the most powerful tools available to an investor is time. Money invested earlier has longer to benefit from potential growth and compounding. Even relatively small regular contributions can build over the years.
‘The best time to start investing was ten years ago.
The second-best time is now.’
Start with where you want to go
Perhaps your children are older now. You may have returned to work, increased your hours or reached a point where you finally have more space to think about your own future.
The gap may be there, but that does not mean it cannot be addressed.
The first step is to understand what you want your money to help you achieve, and when. What are you working towards? When would you like to retire? Do you want to work less before then? Are there things you want to do for your children or family? What would financial security look like to you?
- What do you already have in place?
- What might you need to achieve those goals?
- Is there a gap between the two?
- What are you currently contributing, saving or investing?
- What could you realistically do differently without putting your current family finances under pressure?
Depending on your circumstances, it may be possible to review pension contributions, make better use of workplace benefits, invest more regularly or adjust your longer-term plans.
The right answer will be different for everyone because the life they are planning for is different too.
A Pinnacle LifePlan analyses where you are today with where you want to be. You will see the financial gaps, explore the opportunities with your Adviser and build an actionable plan to get you where you need to be.
You can’t go back and start ten years ago. But you can decide what you want the years ahead to look like, and start planning for them today.
Your financial future deserves your attention.
SJP Approved 17/11/2026
Financial Health Report 2026: Women and Wealth. On behalf of St. James’s Place, Opinium surveyed 6,000 UK adults nationwide between 17 March and 9 April 2026. Quotas and post-weighting were applied to the sample to make the dataset representative of the UK adult population.